Raising Heirs, Not Dependents: Money Education Inside a Wealthy Black Home
How to prepare children for inheriting wealth begins long before a will is ever read. It begins with family money education at your own kitchen table — allowances with architecture, a family bank, a first job, and giving practised like a craft.
Every wealthy family eventually faces the same quiet question: how to prepare children for inheriting wealth without letting the wealth prepare them — badly — for nothing at all. The families who answer it well rarely start with documents.
They start with family money education, delivered the way all durable lessons are delivered in a home like yours: early, repeatedly, and in amounts small enough to practise on.
This piece is general information about how heir-preparation educators, advisers and experienced families approach that education — it is not financial advice for your household, because your household's plan belongs with your own advisers.
But the architecture below is the one the professionals keep returning to, and it starts, as our hero photograph does, with a father, a son, and a statement spread out where breakfast used to be.
The Transfer Is Not Coming. It Is Here.
The scale of what is moving between generations is now measured in the tens of trillions, and the estimates deserve to be stated the way the researchers state them — as ranges with names attached.
SoFi's summary of the Cerulli Associates research puts the figure at approximately $124 trillion in assets expected to transfer by 2048, with about $105 trillion of that passing to heirs and $18 trillion to charity — and, pointedly, more than half of it originating from high-net-worth and ultra-high-net-worth households that make up only about 2% of all households.
Other researchers count differently: reporting covered by Barron's notes the UBS Global Wealth Report's estimate of $83 trillion transferring over the next 20 to 25 years, with liabilities, taxes and giving netted out differently by different firms.
Whichever ledger you trust, the direction is the same, and for Black families building first- and second-generation fortunes the stakes carry an extra weight — Black Enterprise's coverage of the transfer makes the point plainly: preserving assets across generations can depend on whether heirs understand how those assets work, and the goal is to pass down financial knowledge alongside the money.
And yet readiness lags intention almost everywhere researchers look. Barron's report on BNY Wealth's study — a Harris Poll survey of 501 individuals with at least $10 million in investable household assets — found that 48% of those surveyed believe their heirs are only "somewhat prepared," "not very prepared," or "not prepared at all" to handle an influx of wealth.
The same reporting describes the transfer as less a single moment than a prolonged transition, which is precisely why education, not paperwork, is the long pole in the tent.
There's a big disconnect between intention and execution.— Alvina Lo, Head of Advice, Planning & Fiduciary Services at BNY Wealth, via Barron's
First, Retire the Scare Statistic — Honestly
You have heard the famous figures at a dinner party, delivered as fate: 70% of wealthy families lose their wealth by the second generation, 90% by the third. Before building a childhood around fear of them, your family should know what researchers who have examined the claim actually say.
Northland Wealth's review of the evidence traces the 70% figure to its popularisation by Williams and Preisser in Preparing Heirs (2003) and records the correction: in 2022, Dr. Jim Grubman of the UHNW Institute traced the statistic to a single 1987 study of 200 manufacturing businesses in Illinois and argued the methodology was not designed to measure family wealth longevity.
The specific percentage, Northland concludes, is contested — but the underlying principle is not: the primary risks to intergenerational wealth are human, not technical.
The same review notes that multiple research frameworks converge on the same causes — breakdowns in trust and communication within the family, inadequately prepared heirs, and the absence of a shared family mission — while technical failures by professional advisers are consistently a minor factor.
That is the honest version, and it is more useful than the scary one: your children's preparation is not a coin toss against a curse. It is a curriculum you control.
Start With Values, Because Values Are the Curriculum
Every serious programme begins one level above money itself.
Commerce Trust's guidance for high-net-worth families puts it first: preparing heirs begins with educating children on the family's attitudes towards money — the value of work, providing for your family, saving, spending, philanthropy, and continuing the family legacy — and those educational conversations may begin before fully revealing to children the extent of the wealth they will inherit.
The sequence matters. A child who learns what the money is for before learning how much of it there is has a frame to put the number in when it arrives.
Commerce Trust's age-by-age sketch is the one many advisers echo: in childhood, an allowance that rewards completed chores; in adolescence, encouragement toward a part-time job; in young adulthood, personal stories about how your own career choices shaped your life, and the first invitations into the family's real financial conversations.
The Allowance, Built Like Architecture
An allowance in a wealthy home is not pocket money; it is the first managed portfolio, and it should be designed, not dispensed.
PlanCorp's stage-by-stage guide for high-net-worth families makes the design principles explicit: an allowance works as a teaching tool when expectations are clear and consistent — whether your family ties it to household responsibilities or provides a consistent amount as a budgeting exercise — because what matters is that children understand how money is earned, that resources are finite, and that choices require trade-offs.
The specific dollar amount, PlanCorp notes, is far less important than the opportunity to practise independent decision-making in a controlled environment.
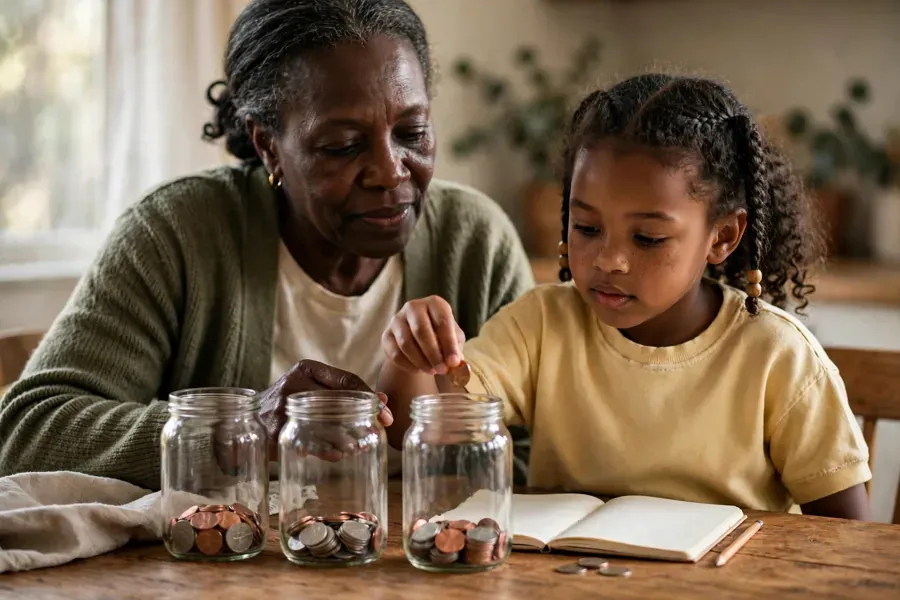
Onto that frame, the same guidance hangs the framework our inset photograph shows in its oldest form — three jars, three destinations: a "Save, Spend, Give" structure that separates money into clear categories, teaches balance and intentionality, and turns waiting for a larger purchase into a lesson in patience rather than a negotiation.
And PlanCorp adds the rule wealthy parents find hardest: allow room for small mistakes. When a purchase breaks quickly or loses its appeal, resist the urge to replace it immediately — the disappointment is the tuition, and it is cheapest now, when the stakes are a toy and not a portfolio.
The Family Bank: Interest, Taught at the Kitchen Table
The natural next institution, once the jars are outgrown, is the family bank — the household-run ledger in which children deposit their savings with their parents and may borrow against future allowance at a real, stated cost.
The White Coat Investor's widely shared account of the practice describes the mechanics families use: children deposit excess earnings or allowance with the parents and borrow when needed, with a high interest rate running in both directions, and monthly reviews in which the parents, as bank directors, go over the balances with their children — so that over time children learn that smart folks earn interest rather than pay it.
The genius of the device is its scale: every concept that will later govern a trust distribution or a margin account — principal, interest, obligation, the quiet pleasure of watching a balance grow — is rehearsed here at kitchen-table size, with a banker who loves the client.
It also creates the family's first regular financial meeting, a habit whose grown-up form we take up in our companion piece on the family meeting.
First Jobs, Earned Money, and the Dignity of a Paycheque
No simulation fully replaces the experience of being paid by someone who owes you nothing. The heir-preparation literature is consistent on this point: earned income teaches what transferred income cannot — the exchange rate between hours and things.
Commerce Trust's progression builds toward it deliberately, encouraging part-time work in adolescence as the bridge between chore-based allowance and adult financial life, and Mercer Advisors' guidance on preparing children to inherit responsibly frames the whole arc the same way: fostering financial literacy, instilling shared family values, and encouraging purposeful stewardship, with structured mentorship and gradual involvement in wealth decisions helping heirs transition into leadership — viewing inheritance as a shared legacy, not just financial gain.
For families with a business, gradual involvement can include real responsibility inside it; for families without one, a summer job chosen by the teenager — not arranged through a family friend into a sinecure — does the same work. The point is not hardship theatre.
It is that a young person who has once budgeted a month on money they earned standing up has a permanent reference price for everything the inheritance will later offer them sitting down.
Trusts as Teaching Tools, Not Just Vaults
When the legal structures arrive, the best-drafted ones are built to keep teaching. Navalign Wealth Partners' guide to preparing children for wealth transfer makes the case directly: trusts are not just legal structures for transferring assets — they can be valuable teaching tools, because a well-designed trust can encourage financial responsibility while gradually preparing heirs to manage wealth independently.
The guide's examples are the shelf most estate attorneys will recognise: incentive trusts that set milestones — completing a degree, maintaining employment — before distributions are made; staggered distributions that release assets over time or in stages, helping heirs learn to manage funds responsibly; and shared decision-making, in which a co-trustee or financial mentor guides heirs until they are ready to take full control.
Used this way, a trust turns the wealth transfer itself into a hands-on learning opportunity rather than a single overwhelming event.
Navalign pairs the structures with the conversation that makes them land: involve heirs in the estate planning process, share the vision behind the plan, clarify the roles heirs may one day assume — trustee, executor, steward of a business or a foundation — and encourage their questions.
A structure a young heir has questioned, and had explained, is one they are far more likely to respect than one announced to them as a surprise.
Philanthropy Chores: Giving as a Practised Skill
In the houses that do this best, giving is not a year-end performance but a chore in the honourable sense — a regular duty with real decisions attached.
Fidelity Charitable's guidance on making giving a family effort describes the vehicle many families use, the donor-advised fund — an account at a sponsoring public charity to which donors contribute, may be eligible for an immediate tax deduction, and from which the family recommends grants to eligible charities on its own timetable, with successor donors named to carry the giving forward.
The guidance quotes practitioner Johnne Syverson's method for the youngest generation: giving young children the power to recommend charities to receive grants of $100 to $500 from the family's fund, researching causes they care about — because, as he puts it, simply watching parents write cheques does not teach core philanthropic values.
The child's grant recommendation, researched and defended at the table, is philanthropy's version of the family bank: real money, real judgement, rehearsal scale. Families who want the fuller architecture — foundations, donor-advised funds and giving that lasts — will find it in our companion piece on philanthropy with structure.
The Conversation Itself — and Why It Cannot Wait
Underneath every structure in this article sits the one practice the research keeps indicting by its absence: talking.
Black Enterprise's transfer coverage cites J.P. Morgan research finding that 70% of family members say they have difficulty approaching conversations about family wealth, with nearly a quarter of younger family members reporting feeling uninformed and about a fifth saying financial discussions are delayed or avoided.
Mercer Advisors' counsel answers that avoidance with a discipline of gradual involvement: begin by teaching heirs the principles of saving, investing and philanthropy; create open dialogues about the origins and intentions of family wealth, emphasising its role as a tool for impact and responsibility; and establish governance frameworks that define roles and discourage entitlement.
None of this requires a single dramatic reveal. It requires a rhythm — the quarterly statement reviewed together, the grant recommended and defended, the job debriefed, the trust explained before it is needed — sustained across the years in which a child becomes the adult your plan assumes.
That, in the end, is the whole difference between an heir and a dependent: the heir was rehearsed. And choosing where that rehearsal happens — the school that will partner with your values rather than compete with them — is the subject of our guide to choosing the school.
For the grace that carries a young person through the harder rooms of this life, see also grace under needles, and meet the builders whose stories fill our Empire Makers collection.
The Family Meeting: Governance for People Who'd Rather Just Love Each Other
Choosing the School
Grace Under Needles
Empire Makers — Profiles Collection
SoFi — "How Will the Great Wealth Transfer Impact Investors?" (Cerulli Associates estimates)
Barron's — "The Great Wealth Transfer Is Taking Longer Than Expected" (BNY Wealth / Harris Poll)
Northland Wealth — "What Determines Whether Family Wealth Survives Across Generations?"
Commerce Trust — "Preparing Heirs for an Inheritance"
PlanCorp — "How High-Net-Worth Families Can Teach Kids About Money at Every Stage"
The White Coat Investor — "How Affluent Parents Can Teach Their Kids About Money"
Mercer Advisors — "How Do We Prepare Children to Inherit Responsibly?"
Navalign Wealth Partners — "Preparing Children for Wealth Transfer"
Fidelity Charitable — "Ways to Help Make Giving a Family Effort"
Black Enterprise — "Women Could Inherit Trillions in the Great Wealth Transfer"
Questions & Answers
What is generational wealth?
How to prepare children for inheriting wealth begins long before a will is ever read. It begins with family money education at your own kitchen table — allowances with architecture, a family bank, a first job, and giving practised like a craft. It links to 5 stories and articles — open any card to read the full piece.
How do families start building generational wealth from zero?
How to prepare children for inheriting wealth begins long before a will is ever read. It begins with family money education at your own kitchen table — allowances with architecture, a family bank, a first job, and giving practised like a craft.
How do I read the full stories on Raising Heirs, Not Dependents: Money Education Inside a Wealthy Black Home?
Choose any card on this page. Each one opens a full page of its own — the complete story or article, with its sources linked.