The Family Meeting: Governance for People Who Love Each Other
A family meeting agenda, an elder's report, a seat kept for the young, and minutes that outlast memory — wealthy families govern themselves the way they run everything else: on purpose, together, and in writing.
Every family talks about money. The question is whether it talks about money in the hallway, in the car, in the heated ten minutes after a holiday dinner goes sideways — or seated, prepared, and on the record.
Families who keep wealth and peace across generations have usually made the same discovery: the family meeting is where the family is actually governed. Not the will, not the trust documents, not the advisers' conference room. A table, an agenda, and the people who love each other, meeting like it matters — because it does.
This is a piece about the meeting itself: the ritual, the roles, and the record. (The heavier machinery that a mature family eventually builds around the meeting — the written constitution, the standing council, the orderly choreography of succession — is its own subject, and we take it up separately in our companion file on the family meeting's constitutional side.)
What follows is general information drawn from family-governance consultants, estate practitioners, and the firms that study wealthy families — not advice for any one household. Your family's version will have your family's fingerprints on it. But the bones of the practice, family after family, are remarkably consistent.
Why a Meeting, and Why on the Calendar
Governance consultants describe regular, well-run meetings as the heartbeat of a family's system — the forum where relationships are maintained, issues are raised while they are still small, and a shared understanding of the family's direction is renewed.
Fusion Wealth Management's guidance on multigenerational meetings makes the point that family meetings are where a family's values and mission are discussed, debated and honed, and that governance structures themselves are often addressed and refined there.
Commerce Trust's family-governance guidance similarly advises that meetings should ideally occur at least annually, with a schedule, an agenda, and someone chosen to lead — and notes that some families hold theirs alongside a vacation or retreat, where the atmosphere does half the diplomacy for free.
The industry has noticed the pattern. Cerulli Associates' survey work, reported alongside Fidelity's family research, found that 89 percent of high-net-worth-focused firms called family meetings one of the most effective transfer-planning practices. That is a striking consensus for an industry that rarely agrees on anything — and notably, the practice costs nothing but intention.
Hewison Private Wealth, writing for families hesitant about formality, lowers the bar to where it belongs:
“A basic family governance structure is really just two things: agreed meetings and shared principles.”— Hewison Private Wealth, on family governance
Agreed meetings. Shared principles. Everything else in this article is decoration on those two load-bearing walls.
The Agenda: Connection First, Business Second
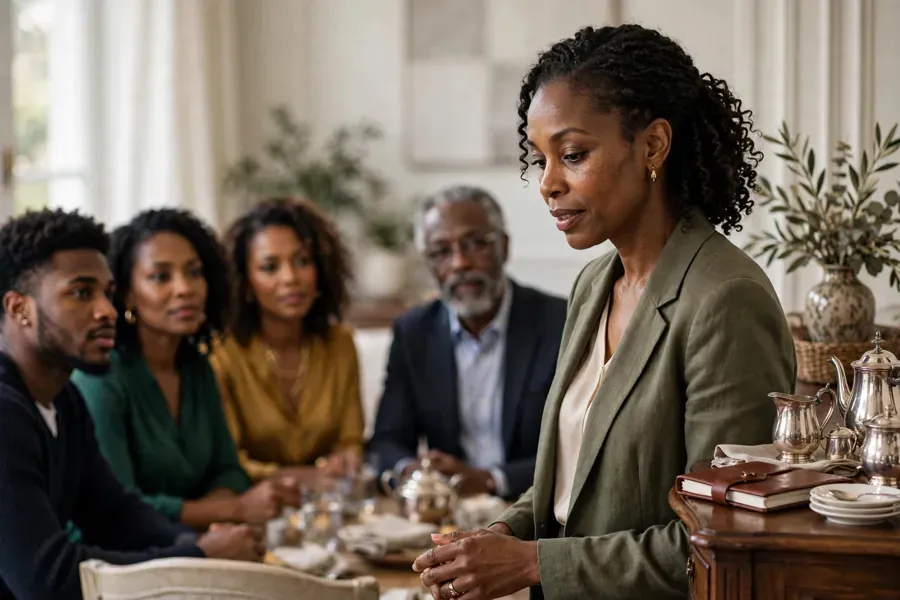
The best family agendas observed by governance advisers share a telling order of business: the family before the finances.
Hing Financial's governance guidance lays out an annual assembly across two movements — a first day given to connection and education, with a welcome, a family heritage presentation, introductions of new members, and workshops, and a second day given to business: a “State of the Family” report, an investment performance review, a philanthropy impact report, then elections, policy proposals, and planning for the year ahead.
Most families compress that into a single long day or a weekend, but they keep the sequence. Heritage before holdings. People arrive as relatives first and stakeholders second, and the meeting goes better for it in ways that are hard to measure and impossible to fake.
Within the business portion, the recurring agenda items across practitioners' templates are consistent: the elder's report — the senior generation's account of the year, the state of the family's affairs, and any decisions the family should understand before it needs to act on them; a plain-language financial overview, presented at the level the whole table can follow; education, with one topic taught properly each year, from how a trust works to how the family business earns its money; philanthropy, its budget and its results; and new ventures or requests, heard in the open rather than lobbied in private.
Fusion's list of common topics adds succession plans, the development of financial literacy in future inheritors, and how new business ventures will be funded — the full working surface of a family's shared life, taken one deliberate item at a time.
The Young People's Seat at the Table
A defining feature of the families who do this well is that the next generation is in the room early — not as audience, but as members with graded responsibility.
Moneyweb's family-governance series puts it plainly: every generation should be represented, from the older members to the younger ones, and its companion governance installment describes regular meetings as the mechanism that includes the younger generation in decision-making while balancing business updates with family bonding.
In practice, the seat comes with a ladder: a teenager reports on the service project she led; a young adult presents the education session he researched; a grandson takes the minutes — a role governance consultants assign real weight, since the person keeping the record is learning the family's business in the most literal way there is.
Our companion piece, Should the Children Know?, traces how much each age is ready to hear; the meeting is where that graduated honesty becomes a standing institution rather than a series of one-off talks.
Roles rotate and are named.
Hing Financial's council guidance assigns the classic officers — a chair who sets the agenda and facilitates, a vice chair, a secretary responsible for minutes and records, and a treasurer for financial oversight — with two-to-three-year terms and staggered rotation to keep perspectives fresh, and a recommendation for outside facilitation when a discussion is sensitive, so that neutrality is built in and every family member can participate fully rather than referee.
Moneyweb's meetings guide adds the humane corollary: the chair's job includes making sure everyone gets a chance to speak — and leadership can rotate every few years, so the meeting belongs to the family, not to its loudest member.
Minutes: The Family's Memory, in Writing
If the agenda is the meeting's courtesy, the minutes are its spine.
Warner Norcross + Judd's family-meeting guidance gives the practice its practical due: note-taking on the main discussion points provides a reference source at future meetings and prevents the twin excuses of “no one told me” and “we never talked about that,” while distributing the minutes gives members a record of what needs doing before the next meeting and a chance to correct the record while memories are fresh.
Moneyweb's guide says the same in fewer words: outcomes should be recorded to ensure accountability, and followed up at the next meeting. This is the unglamorous technology that separates governance from conversation. Decisions written down stop being re-argued.
Commitments with names beside them get kept. And a family that keeps minutes is quietly building an archive its grandchildren will one day read the way other families read photo albums — as the story of how the house was run, and by whom, and how well.
The follow-through matters as much as the record. Practitioners recommend closing each meeting by reviewing action items aloud, assigning an owner and a date to each, gathering brief feedback on the meeting itself, and setting the next date before anyone leaves the table.
Fusion's guidance warns explicitly against treating the meeting as a “one and done” affair: lives change, sometimes suddenly, and the rhythm — annually at minimum, twice a year in many ultra-wealthy families — is what keeps the institution alive.
Videoconferencing, the same guidance notes, is a perfectly respectable bridge when geography argues otherwise; a family scattered across three time zones has no excuse left, and most know it.
One Meeting, Four Movements
Konvergent Wealth Partners, which advises affluent families on exactly these gatherings, suggests thinking of the meeting not as an event but as a four-step process: planning the meeting, conducting it, determining follow-up actions, and assessing outcomes. The framing sounds corporate until you live its absence.
A meeting without the planning step starts late, wanders, and ends with the hardest item untouched. A meeting without the assessment step repeats last year's mistakes with this year's catering.
Treated as a cycle rather than an occasion, the family meeting compounds: each one is slightly better run, slightly more candid, and slightly more trusted than the one before, and the family's confidence in its own governance compounds with it.
The same firm's topic list is a useful mirror for any family drafting its first agenda. Alongside investment and estate updates, it names the concerns of family members that can affect family enterprises, the family's philanthropic activities and how they are funded, and — most tellingly — how business acumen and financial literacy will be developed in future generations.
That last item deserves its own line on every agenda, every year. A family that reports annually on what its young people have learned, and what they will be taught next, has made education a governed commitment rather than a parental hope.
It also gives the young something priceless: visible proof that the elders are preparing the room for them, not merely preserving it from them.
Where distance or temperament argues for help, families increasingly borrow a professional chair for the hardest sessions. Hing Financial's governance guidance recommends independent facilitators for sensitive discussions precisely because neutrality lets every member — including the family's own leader — participate fully instead of presiding.
There is no weakness in that arrangement; judges do not stop being authoritative because a clerk keeps the record. The family that can hire expertise for its portfolio can hire it, occasionally, for its peace.
Guardrails That Keep Love in the Room
A family meeting fails in predictable ways, and governance writers name them so you do not have to discover them. Power concentrated in one pair of hands — the same person leading the family, chairing its meetings, and writing its policies — corrodes accountability and breeds resentment; Moneyweb's governance series lists concentration of power among the common mistakes to avoid.
Meetings called only in crisis teach the family to dread them. And the absence of ground rules — one voice at a time, disagreements addressed to the issue and never to the person, what is said at the table staying at the table — invites the meeting to become the argument it was meant to prevent.
Set the rules once, kindly, and in writing. Then keep them the way you keep everything else in a well-run house: without exception, and without drama.
Starting Small Is Starting
If your family has never held such a meeting, the correct first one is embarrassingly modest.
Hewison's guidance to hesitant families is to keep the machinery light: a council, in its telling, need not be formal at all — for many families it is simply an agreed catch-up once or twice a year, with a loose agenda and everyone's voice in the room, a forum deliberately separate from trustees and company structures, where expectations can be updated as circumstances change and the next generation is brought in gradually rather than all at once.
Commerce Trust adds the setting trick: fold the meeting into a family vacation or retreat, where a relaxed, neutral atmosphere does quiet diplomatic work that no agenda item can. One dinner, honestly chaired, with three questions on paper and the answers written down, is a complete first meeting.
The constitution, the council, the full ceremonial — all of that can grow later, at the pace the family earns. What cannot be recovered later is the habit, and the habit starts the first time the family sits down on purpose.
One last distinction is worth holding onto, and Fusion's advisers state it beautifully in spirit: cohesion is not the same as unity. Families are not required to agree about everything, and a meeting that demands harmony will get performance instead.
What the meeting can honestly deliver is a family on the same page about what it is doing together — its purposes, its decisions, its word to itself. That is governance. For people who love each other, it turns out to be enough — indeed, it turns out to be most of the point.
Should the Children Know? The Money Conversation, by Age
The Family Meeting — the constitution, the council, and succession machinery
Estate Planning Is Love
The Family Reunion, Produced
Empire Builders — the Bourgeois Society profile collection
Hing Financial — “Family Governance & Constitution”
Fusion Wealth Management — “The Value of Multigenerational Family Meetings”
Commerce Trust — “Family Governance: Strengthening Wealth Values & Legacy Planning”
Hewison Private Wealth — “Family Governance: The Conversation Wealthy Families Shouldn't Put Off”
Moneyweb — “Generational wealth, Part 16: Family meetings that actually work”
Moneyweb — “Generational wealth, Part 14: Family governance, the glue that keeps families together”
Warner Norcross + Judd — “Four Best Practices for Holding Successful Family Meetings”
TS2 — “Fidelity Finds Only 37% of Affluent Older Adults Have High Planning Confidence” (Cerulli Associates survey findings)
Konvergent Wealth Partners — “The Power of High-Impact Family Meetings”
Questions & Answers
What is generational wealth?
A family meeting agenda, an elder's report, a seat kept for the young, and minutes that outlast memory — wealthy families govern themselves the way they run everything else: on purpose, together, and in writing. It links to 5 stories and articles — open any card to read the full piece.
How do families start building generational wealth from zero?
A family meeting agenda, an elder's report, a seat kept for the young, and minutes that outlast memory — wealthy families govern themselves the way they run everything else: on purpose, together, and in writing.
How do I read the full stories on The Family Meeting: Governance for People Who Love Each Other?
Choose any card on this page. Each one opens a full page of its own — the complete story or article, with its sources linked.