Should the Children Know? How to Talk to Kids About Family Wealth and Inheritance, by Age
Every established family eventually faces the same quiet question: how to talk to kids about family wealth and inheritance — how much, how soon, and in what words. The families who do it well treat honesty the way they treat everything else in the house: graduated, deliberate, and on a schedule.
It usually arrives without warning. A child counts the houses on the street, or the cars in the drive, or the staff moving through the kitchen, and asks the question plainly: are we rich?
How you answer that question — and how to talk to kids about family wealth and inheritance across the whole of their growing up — may be the most consequential conversation in a wealthy family's life. Not because of the money itself.
Because of what the answer teaches them about who they are, where the money came from, and what it is for.
This article is general information about how established families approach the conversation, drawn from family-governance advisers, child-development specialists, and published research. It is not financial or legal advice for any particular family — that belongs to your own advisers, who know your house.
What it offers is the shape of the practice: what children are ready to hear at eight, at thirteen, at seventeen, and at twenty-five, and why the families who thrive across generations almost never leave the subject to chance.
The Silence, in Numbers
Start with how rare the conversation still is.
Fidelity Investments' Family and Finance research, surveying parents aged fifty-five and older holding at least $500,000 in investable assets, found that 68 percent of parents had not shared inheritance details with their children, even though 70 percent had a will or estate plan in place — and even though 97 percent of families agreed these conversations matter.
A later Fidelity study sharpened the picture further: 81 percent of parents had completed at least one planning document, but only 19 percent had discussed the finished plan with their children. The paperwork, in other words, is largely done. The people expected to live with it have largely not been told.
The reasons parents give are understandable, and advisers hear them constantly: a fear that knowledge will soften a child's ambition, worry about friction between siblings, simple discomfort with putting a number on the table, and — perhaps most honestly — not knowing how to begin. Meanwhile the stakes keep growing.
Cerulli Associates projects that roughly $124 trillion will change hands through 2048, with about $105 trillion flowing to heirs. A transfer of that scale will not pause politely while a family finds its words.
The conversation is coming either way; the only choice is whether it happens around your table, gradually and with love, or all at once, later, in a lawyer's office.
There is a second gap inside the first, and it is the one that makes the silence so costly: the generations do not even agree on whether the children are ready.
In Fidelity's research, the overwhelming majority of adult children — 95 percent in the study's reporting — considered themselves ready to manage inherited wealth, while a quarter of their parents disagreed. Read those two numbers together and you see the actual family problem. It is not that the children are incapable, nor that the parents are careless.
It is that readiness has never been tested in the open, because the subject has never been opened. A child cannot demonstrate stewardship of a responsibility she has never been shown, and a parent cannot assess a readiness he has never allowed to be practised.
The conversation is the test, the training, and the answer, all at once — which is why postponing it protects nothing.
The Question Itself: “Are We Rich?”
Sooner or later the question is asked outright, usually by a child who has simply been paying attention — to the second house, the help in the kitchen, the ease with which big things are paid for.
Fortune's reporting on the families who dread that moment carries a reassurance worth hearing: consultant Jessica McGawley, who has worked with wealthy families for nearly two decades, finds herself explaining to clients that children who ask are not being greedy or rude.
They are doing arithmetic with the evidence in front of them, and they deserve an answer built with the same honesty. McGawley observes that many families produce an airtight paper plan and then never walk their children through it — the document exists, the understanding does not.
How a parent talks about money, she suggests, tends to mirror how that parent handles every other delicate subject: the comfort is a habit, and habits can be built.
The answer that serves a child is neither a figure nor a deflection.
It is a placing: yes, this family has been fortunate, and here is the work that fortune came from; no, that does not set you apart from your friends in the ways that matter; and here is what our money is for — the people it helps, the choices it makes possible, the responsibilities it carries.
A child who hears that answer hears the truth at exactly her size. She will ask again, bigger, in a few years. That is not a failure of the first conversation.
That is the curriculum working.
“Successful families are very good at preparing wealth for the children. They are not good at preparing the children for the wealth.”— Jessica McGawley, founder of Dallington, speaking to Fortune
That sentence, from a consultant who has spent nearly two decades working with wealthy families, is the whole argument in miniature. Preparing the wealth is the advisers' work. Preparing the children is the parents'.
And preparation, like everything else in child-rearing, works best in stages — matched to what a young mind can actually hold.
At Eight: Values Before Figures
No eight-year-old needs a balance sheet. What an eight-year-old needs is a working relationship with money itself — its effort, its patience, and its purposes.
The Consumer Financial Protection Bureau, summarizing developmental research, notes that children as young as five can be developmentally ready to learn about saving, and that children who grow up with a savings account tend to carry stronger financial habits into young adulthood.
The lesson at this age is not the family's wealth; it is the child's own small economy, handled seriously.
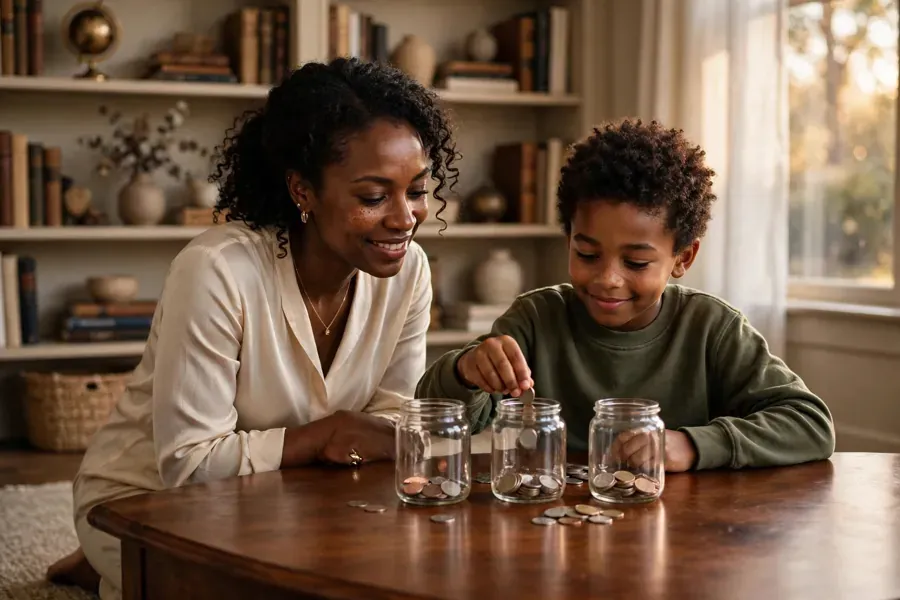
Child-development specialists commonly recommend a simple three-part frame for a child's own money: spend, save, share.
Dr. Siggie Cohen, a child development specialist, describes the spend, save and share system as a concrete framework for decision-making, practising delayed gratification and generosity at once — and treats allowance itself as a learning tool rather than a test of parental approval, with children typically ready for one around ages five to seven.
In a wealthy household, this is where the deeper curriculum hides in plain sight: the child who learns to wait for what she wants, to watch a jar fill slowly, and to set aside a portion for someone else is learning the family's philosophy long before she learns its figures. Speak in principles, not prices.
“In this family, we work, we save, and we help” is a complete sentence for an eight-year-old — and, done consistently, it is never really contradicted by anything she learns later.
At Thirteen: The Shape of the House
The tween and early-teen years are when advisers suggest the conversation widens from the child's own money to the family's story.
Guidance collected by estate-planning practitioners describes the years around ten to twelve as a good time to tell the family story — how the money was made, what the work cost, what earlier generations decided and why — and to introduce the idea that one day the children themselves will carry responsibilities, not merely receive assets.
Legacy Capitals, a firm that trains advisers in wealth-transition work, frames disclosure as a deliberate progression rather than a single reveal: education first, then a macro picture of the family's assets, structures and trusted advisers, without specifying the value of each asset. A thirteen-year-old can understand that the family owns a business, holds property, and gives through a foundation.
She does not need — and most families do not offer — the totals.
This is also the age when the family's values stop being slogans and start being visible decisions. Let her sit in, at the edge, on real ones: which causes the family supports this year and why, what a property purchase means, why a relative was helped in one way and not another. The point is apprenticeship.
She is learning that wealth in this house is administered — thought about, argued over respectfully, and answered for — rather than simply spent. Children who absorb that posture early rarely experience later disclosures as a windfall. They experience them as a promotion.
At Seventeen: Rehearsal for Responsibility
By the later teens, the conversation turns practical, and it turns toward the child's own life. Saving, investing and giving can now be taught with real instruments: a first brokerage account watched together, a summer job whose earnings get the spend-save-share treatment at genuine scale, a seat at the family's giving discussions with an actual vote on an actual grant.
Legacy Capitals' progression also flags the transitions that force the subject anyway — a child's approaching marriage, a business idea, a vocation chosen for love rather than income — and advises that if a family expects a prenuptial agreement one day, that conversation should be preceded by several conversations about values and legacy, so the document arrives as one expression of a philosophy the young person already knows, not as a cold surprise delivered by counsel.
Seventeen is also when honesty about expectations matters most. Will the family help with a first home, and on what terms? Is support for graduate school a gift, a loan, or matched against the child's own saving?
Is there a family business, and is a role in it an invitation, an option, or an assumption to be gently corrected? None of these answers needs to be final. All of them should be spoken.
A young person planning her twenties around assumptions nobody has tested is a preventable heartbreak, and advisers trace a surprising share of family conflict not to greed but to two generations planning from different, unspoken scripts.
At Twenty-Five: The Full Table
In the twenties, graduated honesty reaches its destination: full participation. Practitioner guidance for this stage describes adult children who should know the estate plan itself — what it provides, where the documents live, the reasoning behind the decisions, and an introduction to the family's lawyer and advisers while everyone is well and the meeting is just a meeting.
They should be setting up their own documents, understanding any assistance the family offers during the parents' lifetime and the parameters around it, and hearing their parents' own later-life plans discussed with the same candour.
By their thirties, the guidance concludes, children should be fully involved — which is precisely where the family's formal meeting, the subject of our companion piece, takes over as the room where all of this lives.
None of this requires a single dramatic evening with a reveal. In fact, the families who do it best describe the opposite: a hundred small conversations across twenty years, each one sized to the child in front of them, so that no single talk ever carries more weight than a talk can bear.
The question “should the children know?” turns out to be badly put. The real question is whether they will learn it from you — slowly, in context, with the story attached — or all at once, from circumstance, with the story missing.
The Statistic You Have Heard, Corrected
One famous number haunts this subject, and it deserves an honest footnote. You will hear, at conferences and in advisers' decks, that seventy percent of wealth is lost by the second generation and ninety percent by the third.
The Family Firm Institute's practitioner journal traced that claim to its source and found something thinner than the legend: it rests largely on a 1987 study of family-business longevity, in which a 70 percent “failure” figure is simply the inverse of a 30 percent business-continuity rate — a finding about firms changing hands, later repeated as a law about families losing fortunes, and one that more careful subsequent research has largely dispelled.
Family-wealth psychologist James Grubman, quoted in an examination of the myth, puts the point bluntly: the 70 percent failure rate is “just made-up math.”
“The 70% failure rate is just made-up math.”— Dr. James Grubman, family-wealth psychologist
We retire the number here not to relax anyone, but to aim the concern correctly. Wealth is genuinely lost in families — to silence, to surprise, to children handed responsibility they were never rehearsed for. It is preserved by the unglamorous opposite: early, staged, honest conversation.
No statistic is required to make that case. Your own table, and the questions already being asked across it, make it completely.
The Family Meeting: Governance for People Who Love Each Other
Raising Heirs, Not Dependents
The Family Office Question
The Family Office, Explained
Home for the Holidays, Their House
Empire Builders — the Bourgeois Society profile collection
Savant Wealth Management — “When Parents Refuse to Discuss Estate Plans” (reporting Fidelity's Family and Finance study)
The Wealth Advisor — “Fidelity Says 4 In 5 Parents Are Leaving Heirs Out Of The Estate Plan”
Fortune, via CoreAfric — “‘Are we rich?’ The question billionaire and millionaire parents dread”
SoFi — “How Will the Great Wealth Transfer Impact Investors?” (Cerulli Associates projections)
Consumer Financial Protection Bureau — “Here's why childhood is an important time to learn about money”
Dr. Siggie — “What Child Allowance Spending Actually Teaches”
Trust Counsel — “How and When to Talk to Your Children About Money”
Legacy Capitals Academy — “When to Communicate About Family Wealth”
FFI Practitioner — “A Renewed Call for Accurate Research about Family Wealth Longevity”
Oaks Wealth Management — “The Third Generation Curse That Never Was”
Questions & Answers
What is generational wealth?
Every established family eventually faces the same quiet question: how to talk to kids about family wealth and inheritance — how much, how soon, and in what words. The families who do it well treat honesty the way they treat everything else in the house: graduated, deliberate, and on a schedule. It links to 6 stories and articles — open any card to read the full piece.
How do families start building generational wealth from zero?
Every established family eventually faces the same quiet question: how to talk to kids about family wealth and inheritance — how much, how soon, and in what words. The families who do it well treat honesty the way they treat everything else in the house: graduated, deliberate, and on a schedule.
How do I read the full stories on Should the Children Know? How to Talk to Kids About Family Wealth and Inheritance, by Age?
Choose any card on this page. Each one opens a full page of its own — the complete story or article, with its sources linked.